We settle large-loss property damage insurance claims
Commercial Claims
Multi-Family Claims
High-Value Home Claims
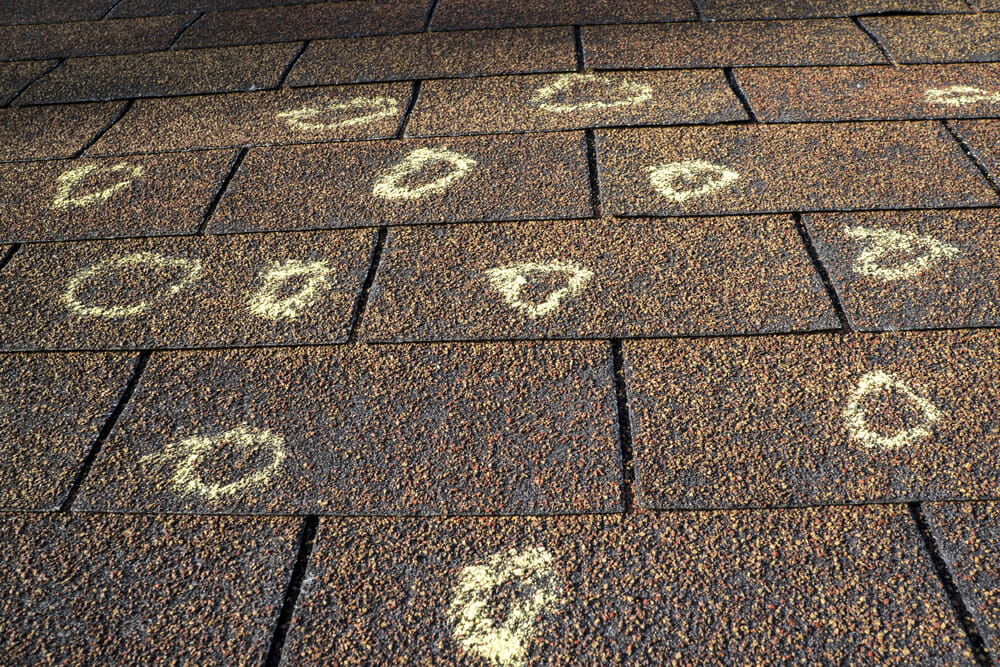
Managing Hail Damage Losses
Trust ICRS public adjusters to settle your hail property damage insurance claim
When hail has devastated your property, call ICRS public adjusters to settle your hail claim. We can help you put the pieces back together.
- Commercial Property Hail Claims
- Multi-Family Property Hail Claims
- High-Value Homes & Real Estate Hail Claims
Public Adjuster for Hail Claims
Hail Damage Insurance Claims
Maximizing Your Hail Damage Insurance Claim with ICRS
When dealing with commercial or multifamily hail damage building and roof insurance claims, hiring ICRS Public Insurance Adjusters can make a significant difference in the outcome of your claim. This web page outlines the benefits of hiring ICRS Public Insurance Adjusters, the ideal time to do so, and the importance of proper representation throughout the claim process.
When to Hire ICRS Public Insurance Adjusters
The best time to hire ICRS Public Insurance Adjusters is at the beginning of the claim process. Doing so ensures that your claim is documented properly, helping you get a fair and prompt settlement.
Benefits of Hiring ICRS Public Insurance Adjusters
- Time and Money Savings
- Ensuring Proper Interpretation of Policy Language
- Access to Professional Opinions and Resources
- Support in Navigating Bad-Faith Insurance Practices
- Streamlined Claim Process and Documentation
- Skilled Negotiation for Large Loss Insurance Claims
Free Hail Insurance Claim Evaluation
ICRS offers a complimentary hail report, policy review, and building inspection to help you assess the potential damage and validity of your claim. Click here to get started.
Leveling the Playing Field with Your Insurance Company's Adjuster
By hiring ICRS Public Insurance Adjusters, you ensure that you have experienced professionals working exclusively in your best interests, leveling the playing field against the insurance company’s adjuster.
We hold HAAG Commercial Roof Inspector and IICRC WRT certifications in addition to public adjuster licenses in multiple states.
ICRS routinely settles complex multi-million dollar hail claims. If you own or manage an HOA, Multifamily apartment complex, food plant, storage facility, high-value home, or other commercial property, you’re no stranger to risk management. When your real estate asset suffers a hail damage insurance claim, managing risk and knowing your policyholder rights is critical to getting the fair and prompt settlement you deserve.
Large Commercial and Multifamily hail damage insurance claims can be complex, time-consuming, frustrating, and expensive if you don’t have professional guidance and representation. Know your rights and know your settlement options.
You wouldn’t hire the I.R.S. to prepare your tax returns so why allow your insurer to prepare your insurance claim?
Non-Litigious Approach to Settling Insurance Claims
ICRS takes a non-litigious approach to settling insurance claims, helping commercial and multifamily policyholders receive fair settlements while avoiding unnecessary litigation and appraisals.
Re-opening and Supplementing Underpaid Claims
If you are dissatisfied with your insurer’s settlement offer, ICRS can re-open and supplement your claim to help you receive the fair and prompt settlement you deserve.
Hail Damage Claims
Dealing with hail damage building and roof insurance claims can be a daunting process. However, by hiring ICRS Public Insurance Adjusters, you can maximize your claim, save time and money, and ensure that your interests are protected. Contact ICRS today at 832-725-2878 to get the fair and prompt settlement you deserve.
Preparing for Future Property Damage Claims
While it’s crucial to address current fire damage claims, it’s also important to prepare for potential future claims by understanding your insurance policy and assessing your risk management strategies. Review your policy regularly to ensure you have adequate coverage and consider making updates or adjustments as needed. By being proactive, you can minimize the financial impact of property damage and protect your assets.
Dealing with fire damage insurance claims can be a challenging and stressful experience, especially when you’re faced with complex policy language, differing interpretations, and potential disputes. By working with a public adjuster and a certified hygienist, you can ensure that your interests are well-represented, and you receive the fair and prompt settlement you deserve. Additionally, take the time to review your insurance policy and risk management strategies to minimize the impact of future property damage claims.
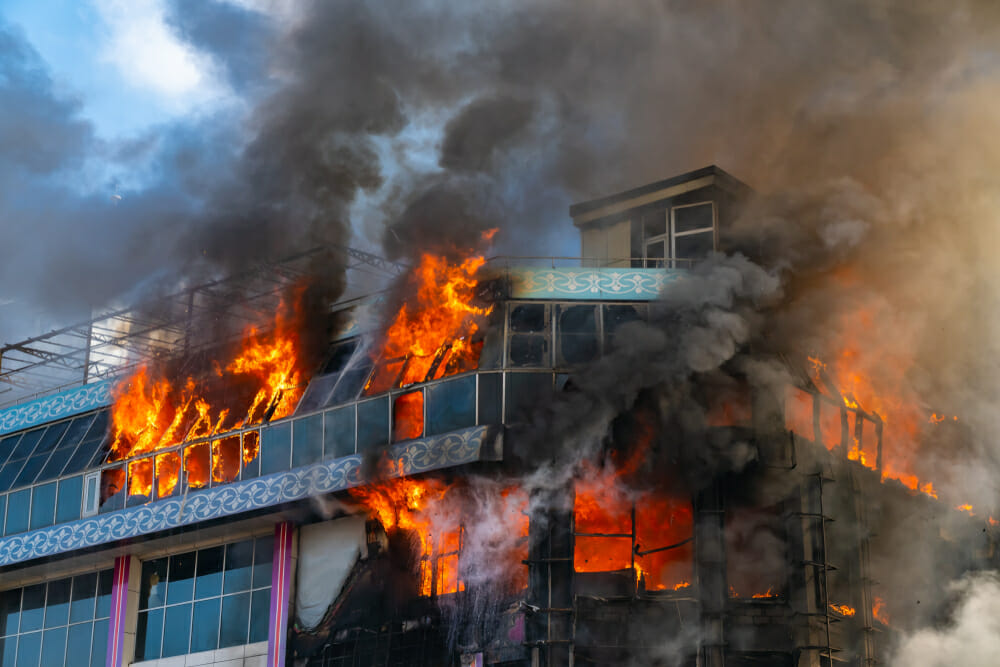
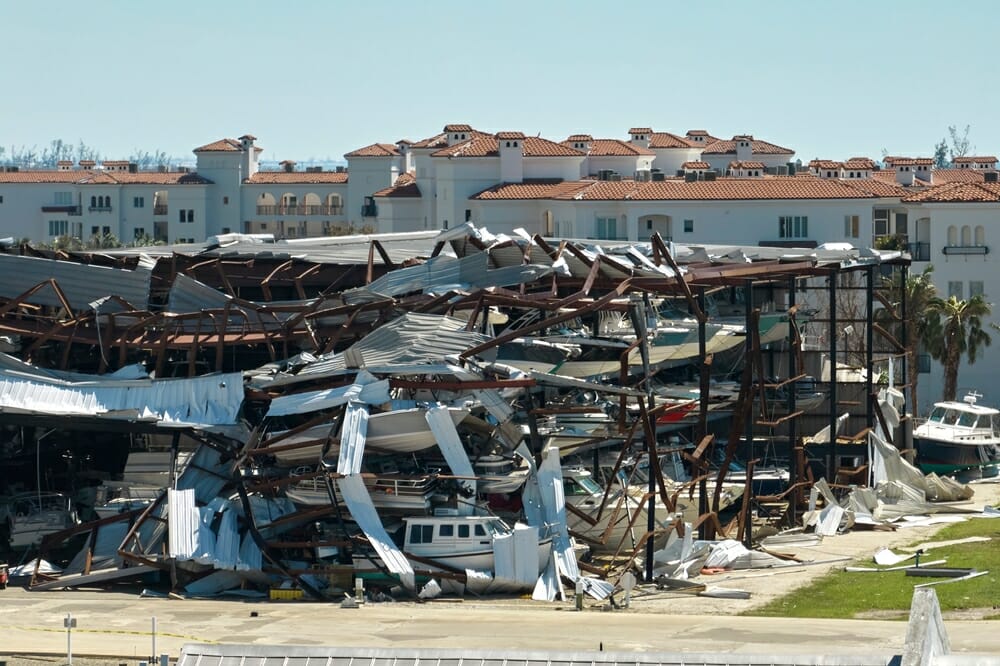
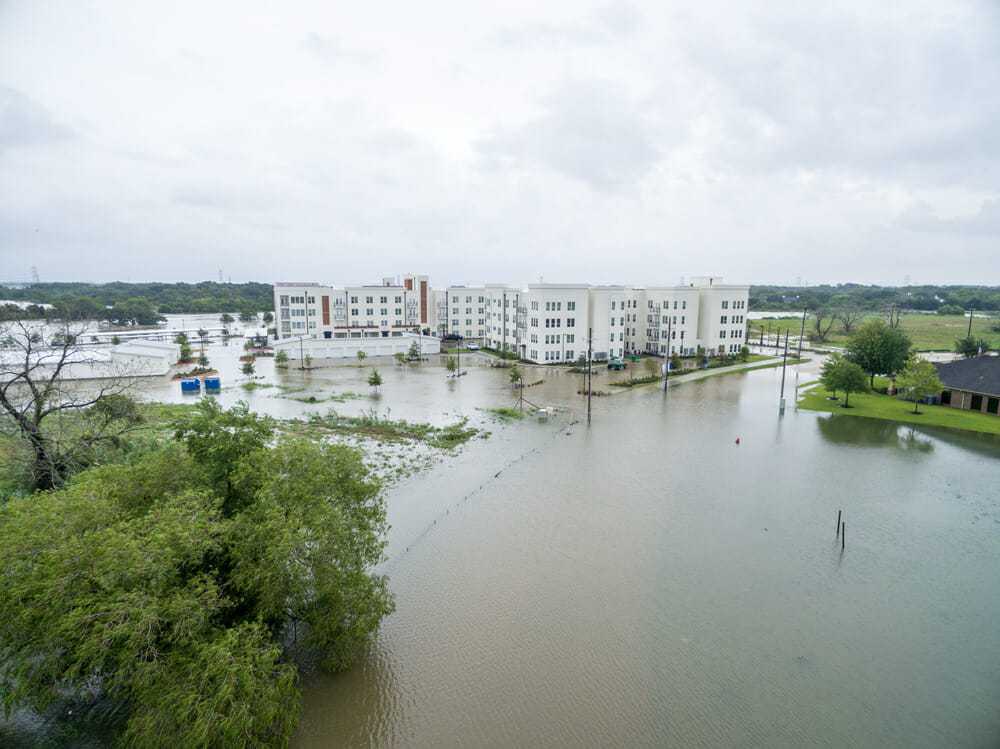
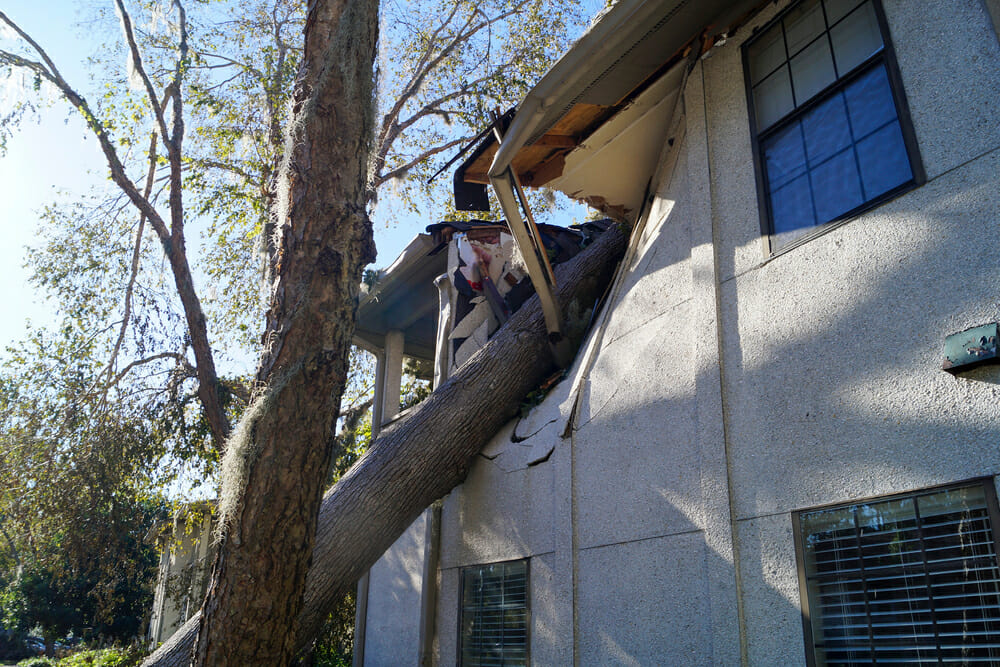
Reasons why insurers deny or underpay insurance claims for hail damage
Reason 1: Lack of documentation
Reason 2: Poorly Maintained Roofs
Reason 3: Unclear policy language
Don’t let this happen to you! Take action now and protect your business. To ensure that your roof hail claim is not denied or underpaid, it is important to have a detailed record of all roof maintenance and repairs, including photos, dates, and descriptions. Additionally, it is important to thoroughly read and understand the language of your insurance policy to ensure that you are aware of any exclusions or limitations that may apply.
Numerous factors affect how a roof covering responds to hail events. Some of these include the roof covering’s age, type, quality, condition, and supporting material as well as variable storm attributes such as hail density, wind direction, and angle of impact.
What are common reasons why insurers deny or underpay hail and wind roof insurance claims?
There are several common reasons why insurers may deny or underpay hail and wind roof insurance claims:
- Damage not meeting the deductible: Many insurance policies have a deductible that must be met before the insurance company will pay for any damages. If the cost of the repairs is less than the deductible, the insurance company will not pay out the claim.
- Pre-existing damage: Insurance companies may deny claims for damage that was present on the roof prior to the storm. Policyholders need to have a clear understanding of the condition of their roof prior to filing a claim.
- Failure to maintain the roof: Insurance companies may also deny claims if the Policyholder has not properly maintained the roof. This could include failing to repair leaks or replacing damaged shingles.
- Age of the roof: Insurance policies may have restrictions on coverage for older roofs. If the roof is past a certain age, the insurance company may only pay for a partial replacement, rather than a full replacement.
- Dispute over the cause of the damage: Insurance companies may dispute the cause of the damage, especially if there were other factors at play, such as poor installation, deferred maintenance, improper installation, or inadequate ventilation.
- Incomplete or inadequate documentation: Insurers require detailed documentation of the damage, including photographs and repair estimates, to support the claim. Failure to provide sufficient documentation can result in a denial or underpayment of the claim.
It is important for home and business owners to review their insurance policies carefully and to work with an experienced contractor to ensure that all necessary repairs are documented and completed to the insurer’s satisfaction.
- Impact tests and field observations have shown that for laminated, glass-fiber reinforced asphalt shingles, hailstones striking perpendicular to the roof surface must be frozen solid and 1 -1/4 inch in diameter or larger before bruises (fractures in the reinforcement mat) and punctures are likely to occur.
- Hail impacts on a TPO roof system are characterized by tears and punctures or fractures of the single-ply membrane.
- Many roofing tiles are designed with a longitudinal interlock to allow proper water shedding in order to match the current surface elevation. The high kinetic energy of the hail impact on the lower corner of the roof tile can cause a point load break, or crack at the over lock corners. This is not a manufacturing defect of the product, but a point-loading impact that has occurred in a concentrated area.
- Polymer-modified bitumen membranes are composed of fiberglass and/or polyester reinforcement, and their top surfaces are protected by surfacing such as factory embedded granules, factory-bonded foils or field-applied coatings. Hailstones of sufficient size and hardness can puncture, tear or bruise a polymer modified bitumen membrane where they strike and reduce the membrane’s weatherproofing capability. A roof system’s expected service life can be reduced when hail disrupts the membrane’s protective surfacing and exposes its coating bitumen.
- Lastly, it is important to document all hail damage and file your claim as soon as possible.
When filing your commercial or multifamily building hail damage insurance claim, Policyholders need the evidence necessary to support all damages. Insurance Claim Recovery Support helps policyholders document damages and negotiate the insurance policy benefits they have paid for.
HAIL LOSS INSURANCE CLAIMS
How to Prepare for Hail Damage
Before the Storm
• Trim tree branches so they don’t rub on the roof;
• Maintain roof per manufacturer recommendations and contractor repair recommendations;
• Remove debris from your roof, gutters and downspouts;
• Get your roof inspected prior to storm season. A little problem can turn into a BIG PROBLEM;
• Place any items from outside indoors. Small Items have a chance to fly around in high winds and you want to protect as many items as possible;
• Take advantage of our complimentary Risk-Free building inspection before storm season begins.
During the Storm
• Close all windows and cover them up. You don’t want glass flying in.
• Stay indoors, away from skylights and doors.
• Hailstorms can be a warning sign for tornadoes. If the sky is getting dark and you start to hear a loud roar, take shelter in case a tornado is on its way.
After the Storm
• Check property for potential direct hail and/or wind damage;
– Missing shingles, indentations in roof materials;
– Broken windows or siding;
– Dents in gutters, downspouts and air conditioning units;
– Water intrusion to interior.
• Indications of collateral damage
– Damage to trees, fences, landscaping and vehicle dents.
• Take pictures of all damages.
• Contact your insurer or insurance agent and put them on notice you intend to file a hail insurance claim.
• MITIGATE DAMAGES as soon as possible.
• Keep records of mitigation and clean up expenses.
Years Experience
Claims Settled
Hours Worked
Average Claim Amount
Risk-Free Loss Recovery Offer
Get a complimentary consultation on your damage insurance claim. We are public claim adjusters who work for policyholders, not the insurance company. If you choose to hire us, we work on contingency. No recovery, no fee. Our insurance claim process is proven and streamlined. We also value your privacy. We do not sell, trade, or rent your personal information to others.
Need immediate fire damage insurance claim help?
TESTIMONIALS
What Client Says About ICRS
Trustindex verifies that the original source of the review is Google. Scott and his entire team so incredibly knowledgeable, their is no way we could have accomplish what we did without their guidance. Keep us the great work!!!!!Posted onTrustindex verifies that the original source of the review is Google. Outstanding service experience!!!Posted onTrustindex verifies that the original source of the review is Google. They are truly a Lifesaver! I cannot say enough good things about Insurance Claim Recovery Support — they truly feel like earth angels. Misty and Scott helped me through one of the most overwhelming and helpless times of my life. As a single woman dealing with major home renovations after a severe water leak, I was unfortunately taken advantage of by a dishonest contractor. From breaking my TV and not saying a word, to lying about repairs, damaging my sprinkler, inflating estimates with bogus charges, and even threatening legal action — I was completely overwhelmed. That’s when Misty and Scott stepped in. Their knowledge of the laws and the insurance claims process is unmatched, and their compassion and support were exactly what I needed. They knew exactly how to handle the situation, empowered me with the facts, and guided me every step of the way. They genuinely listened, made me feel heard and understood, and stood by my side when I needed it most. I am beyond grateful for their integrity, expertise, and kindness. If you’re facing a tough insurance claim situation, do not hesitate to reach out to them — they are absolute professionals and true advocates and helped me feel safe in my own home again.Posted onTrustindex verifies that the original source of the review is Google. Not sure how Misty has 5 stars here. She won’t even return a call or email.Posted onTrustindex verifies that the original source of the review is Google. I spoke with Scott about a commercial claim, and he was incredibly helpful. He provided detailed explanations about how policies and adjustments work, making everything much clearer. I really appreciated his thoroughness and knowledge!Posted onTrustindex verifies that the original source of the review is Google. After a nightmare experience dealing with an underpaid commercial property insurance claim from a hailstorm in Dallas, we were fortunate enough to find Scott and Misty Friedson at Insurance Claim Recovery Support (ICRS). Had we not hired them, we would’ve left $127,000 on the table - money we didn’t even know we were owed. Scott and Misty are absolute professionals. Their knowledge of the insurance claim process is unmatched, and they navigated our case with skill, integrity, and relentless attention to detail. On top of that, they’re HAAG certified roof inspectors, which made all the difference in proving the true extent of our damages. Looking back, we wish we had hired ICRS from the very beginning. It would have saved us so much stress, time, and lost money. If you’re dealing with an insurance claim - especially a commercial one - don’t wait. Call ICRS. We’re beyond grateful for everything they did for us.Posted onTrustindex verifies that the original source of the review is Google. ICRS has been a beacon of hope during one of the most challenging times in my life. After my home was struck by lightning nearly nine months ago, dealing with USAA has been nothing short of a nightmare. They have grossly underpaid my claim, and I was at my wit’s end after countless hours of research, discussions with attorneys, and trying to figure out how to rebuild my home without compromising my financial future. Scott and Misty from ICRS have been the most honest, supportive, and knowledgeable people I’ve encountered throughout this ordeal. They made me feel heard and understood, which was a welcome relief after so many interactions with professionals who seemed more interested in their bottom line than in helping me. Scott guided me through this incredibly complex and stressful process with expert advice, giving me the clarity and confidence I desperately needed. His and Misty’s commitment to doing what’s right for their clients is unmatched. They genuinely care and provide guidance and support that feels personalized and sincere. Thanks to Scott and Misty, I’m back on track and no longer feel overwhelmed. ICRS has saved me countless hours of stress and struggle, and I wholeheartedly recommend them to anyone dealing with a large-loss claim after a storm. Trust me—making them your first call can save you immeasurable frustration and help you navigate this difficult path with sound advice and unwavering support. Thank you, Scott and Misty, for everything you’ve done! -Jason CheshirePosted onTrustindex verifies that the original source of the review is Google. Found this firm very responsive with honest advice. Based on our discussion, I actually did not hire them, at least yet, because my claim doesn't require the service. They easily could have pushed to sign me up, but did not. We have just gone thru flooding of our home and it is appreciated not being taken advantage of now.Posted onTrustindex verifies that the original source of the review is Google. Amazing service and results!Posted onTrustindex verifies that the original source of the review is Google. In 2023, our family woke up to a nightmare. Our house was filled with smoke and on fire. We able to get our son and pets out of the burning house without injury, and our local fire department arrived quickly and put out the fire. By the time that the fire was out, most of our home was destroyed. We contacted our insurer to start a claim and were immediately met with opposition and confusion on their part. It took several weeks for them to assign an adjuster to our claim. This initial experience led our decision to hire a Public Adjuster to navigate the process and advocate on our behalf. We couldn’t trust that our insurer would handle the claim responsibly, and we quickly realized that we needed someone to fight for us to hold them accountable to our policy. We were extremely fortunate to find ICRS and secure Scott as our Public Adjuster. Our Insurer mislead us and withheld information. It took weeks for them to provide a copy of our policy, and when they did, they excluded information that benefited us. ICRS pressured them to provide a full copy of our policy which included the benefits they had initially excluded. Our Insurer provided a scope that was not aligned with the actual cost of rebuilding our home. ICRS countered with a realistic scope and advised us to secure independent quotes on our own. ICRS then leveraged its scope and the independent quotes to force our insurer to provide more realistic amount for the rebuild. The scoping process took months, and ICRS drove the communications the entire time. The first adjuster that our insurer assigned to our claim arrived at the site visit and interview with a combative attitude, where he used inappropriate language, and attempted to force the negotiations their favor by manipulating the facts. ICRS swiftly called out the adjuster and guided the negations back on track. Our Insurer cycled through four adjusters during our claim. The pass-down of information between these adjusters was insufficient, with each new adjuster attempting to avoid payout using the same methods that failed with the last. We were astonished that a company could act in this manner without serious recourse. ICRS was able to leverage emails, photos, inspection reports, and additional documentation to bring the adjusters up to speed after each transition. ICRS’ efforts kept the claim moving every time our insurer attempted to stall. When our Insurer misrepresented the policy and refused to pay out for damages that were covered, ICRS drove the communications process and provided documentation, which included case-law excerpts from similar claims that had gone to trial. This approach provided breakthroughs on vital areas of the negotiations. ICRS provided a paper trail and documentation that our Insurer couldn’t ignore, and ultimately they were forced to pay out due to the exposure that ICRS had made apparent. ICRS increased the overall claim by more than 20% during the planning and rebuild process through supplements. Through negotiations with our Insurance company, ICRS increased the claim by 104% over what was released up-front in our initial settlement. Additionally, the payout ICRS secured for us was 31% higher than our policy limit. Before that fire, we had heard insurance companies pull out every trick in the book to avoid paying out on a policy. Having gone through this experience, we can say that the behavior on our insurers part was far worse than we had ever imagined possible. We advise with 100% conviction that anyone dealing with a large loss such as ours, hire a public adjuster to navigate and advocate on their behalf in order to get the needed results. Our family could not have rebuilt our home with the funds our insurance company provided, and we only have a home to return to because of ICRS’ efforts to hold our insurer accountable for the policy we had paid for. Throughout the claim, which lasted over a year, ICRS navigated the entire claim process with professionalism and care. Our family offers a sincere thank you to Scott, Misty, and the entire ICRS team.
FAQs
Frequently Asked Questions
What is a public adjuster and what do they do?
Here at ICRS, we help policyholders understand their rights. Discover the different types of insurance, the insurance claim process, and settlement tips from the National Association of Insurance Commissioners.
When should I hire a public adjuster?
How are public adjusters compensated?
How do public adjusters differ from insurance company adjusters?
Do I need a public adjuster if I already have an insurance agent or broker?
NEWS & ARTICLES
The Latest News
Read More
Read More
Read More