We settle large-loss property damage insurance claims
Commercial Claims
Multi-Family Claims
High-Value Home Claims
Insurance Claim Experts
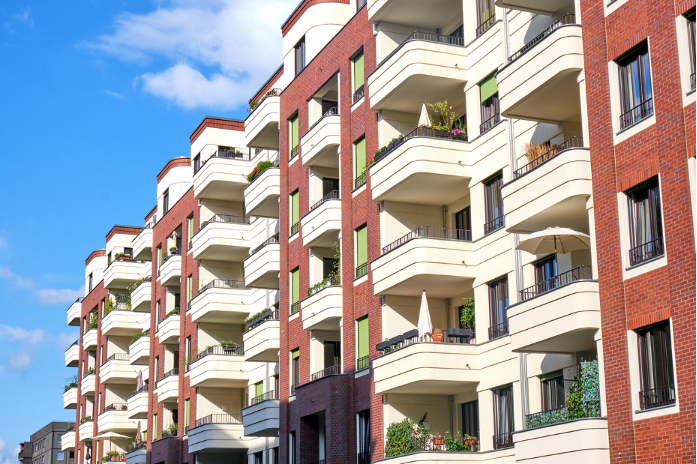
Condominium & Homeowner Association Insurance Claim Assistance
HOA insurance claim loss adjusting processes can wear out even the most vigilant HOA board. The nuances between your master policy and individual owner policies can be confusing. The complexities involved with Condominium association claims often lead to frustrations and time elements most people simply cannot handle on their own.
ICRS public insurance adjusters for condominium associations are dedicated to assisting homeowner volunteers who govern community associations and the professionals who support them to settle insurance claims fairly and promptly. Determining loss assessment coverage under an HOA insurance policy for fire and storm damage insurance claims as well as understanding the condo association master HO6 insurance policy vs. a homeowner HO3 insurance policy can be complex and confusing. We’ve helped numerous homeowners association board members, community managers, and association management firms navigate the insurance claim process.
- Commercial Property Claims
- Multi-Family Property Claims
- High-Value Homes & Real Estate Claims
How our Public Adjusters help your HOA insurance claim:
- We reduce stress by answering your important questions and putting together an actionable plan;
- We exclusively represent your community’s interests and serve as your claim advocate;
- We streamline the claim process so your community gets the fair and prompt settlement it deserves.
HOA Insurance Claim Tips
What does the condo association or HOA master insurance policy cover?
Typically, all common areas in a condominium building are covered under a “master insurance policy” purchased by the condo association or HOA. Usually the building’s roof and exterior but also internal areas such as elevators and hallways are covered.
There are three main types of condo master insurance policies:
- Bare walls coverage is a limited master insurance policy that covers the structure, as well as most fixtures and furnishings in common areas. It also covers any property that is collectively owned by the condo association.
- Single entity coverage offers everything included in bare walls coverage and also provides coverage for built-in property such as fixtures in individual condo units.
- All-in coverage applies to all property collectively owned by the condo association or which is part of the condominium structure. It’s the most comprehensive condo master insurance policy, covering all condo improvements and additions.
The division of ownership and insurance coverage between condo owners and condo associations can present questions when damage affects more than one area of a condo building.
The Difference Between an Individual Condo Insurance Policy and a Master Insurance Policy
Insuring a condominium is unique in that it involves multiple policies, and we understand that this can be confusing. An individual condo insurance policy, or a unit owner’s policy, is the insurance policy that the individual condominium or HOA owner is responsible for their individual unit. This policy essentially protects personal belongings and offers liability protection in case of an accident within the walls of a unit.
Master Condo Policy or Condo Association Insurance is the insurance policy that is held by the homeowners or condominium association. The premium comes out of maintenance fees or association dues. The Master Condo Policy is responsible for covering two main areas of risk — general liability for the association and property damage coverage for common areas. Common areas are generally defined as the roof and exterior walls, stairways, recreation rooms, elevators, common hallways, and grounds.
Typically, a condo owner is expected to pay a condominium association fee that in part covers property insurance for the exterior and common areas of the complex, such as the pool area or deck. This policy, known as a master policy, usually comes in three different types:
- Bare walls-in policy – This is the least inclusive of the policies. It covers the exterior framing of your unit, plus all collectively owned items and structures. It does not cover appliances and fixtures inside the condo. This policy necessitates that the condo owner buys a more comprehensive policy for his or her own possessions.
- All-inclusive coverage policy – This more inclusive option covers all repairs needed to return a unit to the state it was in before the property damage, including appliances, fixtures, and any improvements that the condo owner may have made to the structure.
- Single entity coverage policy – This policy generally covers all property contained in the complex, with the exception of the individual condo owners’ personal property (furniture, etc.). While it covers appliances and fixtures, it does not cover the owners’ improvements or renovations.
Our public adjusters have helped many HOAs and Condominium Associations from disasters of all types and sizes. Contact us today for a free claim review and learn how we can help
Years Experience
Claims Settled
Hours Worked
Average Claim Amount
Risk-Free Loss Recovery Offer
Get a complimentary consultation on your damage insurance claim. We are public claim adjusters who work for policyholders, not the insurance company. If you choose to hire us, we work on contingency. No recovery, no fee. Our insurance claim process is proven and streamlined. We also value your privacy. We do not sell, trade, or rent your personal information to others.
Need immediate fire damage insurance claim help?
TESTIMONIALS
What Client Says About ICRS
Trustindex verifies that the original source of the review is Google. Scott and his entire team so incredibly knowledgeable, their is no way we could have accomplish what we did without their guidance. Keep us the great work!!!!!Posted onTrustindex verifies that the original source of the review is Google. Outstanding service experience!!!Posted onTrustindex verifies that the original source of the review is Google. They are truly a Lifesaver! I cannot say enough good things about Insurance Claim Recovery Support — they truly feel like earth angels. Misty and Scott helped me through one of the most overwhelming and helpless times of my life. As a single woman dealing with major home renovations after a severe water leak, I was unfortunately taken advantage of by a dishonest contractor. From breaking my TV and not saying a word, to lying about repairs, damaging my sprinkler, inflating estimates with bogus charges, and even threatening legal action — I was completely overwhelmed. That’s when Misty and Scott stepped in. Their knowledge of the laws and the insurance claims process is unmatched, and their compassion and support were exactly what I needed. They knew exactly how to handle the situation, empowered me with the facts, and guided me every step of the way. They genuinely listened, made me feel heard and understood, and stood by my side when I needed it most. I am beyond grateful for their integrity, expertise, and kindness. If you’re facing a tough insurance claim situation, do not hesitate to reach out to them — they are absolute professionals and true advocates and helped me feel safe in my own home again.Posted onTrustindex verifies that the original source of the review is Google. Not sure how Misty has 5 stars here. She won’t even return a call or email.Posted onTrustindex verifies that the original source of the review is Google. I spoke with Scott about a commercial claim, and he was incredibly helpful. He provided detailed explanations about how policies and adjustments work, making everything much clearer. I really appreciated his thoroughness and knowledge!Posted onTrustindex verifies that the original source of the review is Google. After a nightmare experience dealing with an underpaid commercial property insurance claim from a hailstorm in Dallas, we were fortunate enough to find Scott and Misty Friedson at Insurance Claim Recovery Support (ICRS). Had we not hired them, we would’ve left $127,000 on the table - money we didn’t even know we were owed. Scott and Misty are absolute professionals. Their knowledge of the insurance claim process is unmatched, and they navigated our case with skill, integrity, and relentless attention to detail. On top of that, they’re HAAG certified roof inspectors, which made all the difference in proving the true extent of our damages. Looking back, we wish we had hired ICRS from the very beginning. It would have saved us so much stress, time, and lost money. If you’re dealing with an insurance claim - especially a commercial one - don’t wait. Call ICRS. We’re beyond grateful for everything they did for us.Posted onTrustindex verifies that the original source of the review is Google. ICRS has been a beacon of hope during one of the most challenging times in my life. After my home was struck by lightning nearly nine months ago, dealing with USAA has been nothing short of a nightmare. They have grossly underpaid my claim, and I was at my wit’s end after countless hours of research, discussions with attorneys, and trying to figure out how to rebuild my home without compromising my financial future. Scott and Misty from ICRS have been the most honest, supportive, and knowledgeable people I’ve encountered throughout this ordeal. They made me feel heard and understood, which was a welcome relief after so many interactions with professionals who seemed more interested in their bottom line than in helping me. Scott guided me through this incredibly complex and stressful process with expert advice, giving me the clarity and confidence I desperately needed. His and Misty’s commitment to doing what’s right for their clients is unmatched. They genuinely care and provide guidance and support that feels personalized and sincere. Thanks to Scott and Misty, I’m back on track and no longer feel overwhelmed. ICRS has saved me countless hours of stress and struggle, and I wholeheartedly recommend them to anyone dealing with a large-loss claim after a storm. Trust me—making them your first call can save you immeasurable frustration and help you navigate this difficult path with sound advice and unwavering support. Thank you, Scott and Misty, for everything you’ve done! -Jason CheshirePosted onTrustindex verifies that the original source of the review is Google. Found this firm very responsive with honest advice. Based on our discussion, I actually did not hire them, at least yet, because my claim doesn't require the service. They easily could have pushed to sign me up, but did not. We have just gone thru flooding of our home and it is appreciated not being taken advantage of now.Posted onTrustindex verifies that the original source of the review is Google. Amazing service and results!Posted onTrustindex verifies that the original source of the review is Google. In 2023, our family woke up to a nightmare. Our house was filled with smoke and on fire. We able to get our son and pets out of the burning house without injury, and our local fire department arrived quickly and put out the fire. By the time that the fire was out, most of our home was destroyed. We contacted our insurer to start a claim and were immediately met with opposition and confusion on their part. It took several weeks for them to assign an adjuster to our claim. This initial experience led our decision to hire a Public Adjuster to navigate the process and advocate on our behalf. We couldn’t trust that our insurer would handle the claim responsibly, and we quickly realized that we needed someone to fight for us to hold them accountable to our policy. We were extremely fortunate to find ICRS and secure Scott as our Public Adjuster. Our Insurer mislead us and withheld information. It took weeks for them to provide a copy of our policy, and when they did, they excluded information that benefited us. ICRS pressured them to provide a full copy of our policy which included the benefits they had initially excluded. Our Insurer provided a scope that was not aligned with the actual cost of rebuilding our home. ICRS countered with a realistic scope and advised us to secure independent quotes on our own. ICRS then leveraged its scope and the independent quotes to force our insurer to provide more realistic amount for the rebuild. The scoping process took months, and ICRS drove the communications the entire time. The first adjuster that our insurer assigned to our claim arrived at the site visit and interview with a combative attitude, where he used inappropriate language, and attempted to force the negotiations their favor by manipulating the facts. ICRS swiftly called out the adjuster and guided the negations back on track. Our Insurer cycled through four adjusters during our claim. The pass-down of information between these adjusters was insufficient, with each new adjuster attempting to avoid payout using the same methods that failed with the last. We were astonished that a company could act in this manner without serious recourse. ICRS was able to leverage emails, photos, inspection reports, and additional documentation to bring the adjusters up to speed after each transition. ICRS’ efforts kept the claim moving every time our insurer attempted to stall. When our Insurer misrepresented the policy and refused to pay out for damages that were covered, ICRS drove the communications process and provided documentation, which included case-law excerpts from similar claims that had gone to trial. This approach provided breakthroughs on vital areas of the negotiations. ICRS provided a paper trail and documentation that our Insurer couldn’t ignore, and ultimately they were forced to pay out due to the exposure that ICRS had made apparent. ICRS increased the overall claim by more than 20% during the planning and rebuild process through supplements. Through negotiations with our Insurance company, ICRS increased the claim by 104% over what was released up-front in our initial settlement. Additionally, the payout ICRS secured for us was 31% higher than our policy limit. Before that fire, we had heard insurance companies pull out every trick in the book to avoid paying out on a policy. Having gone through this experience, we can say that the behavior on our insurers part was far worse than we had ever imagined possible. We advise with 100% conviction that anyone dealing with a large loss such as ours, hire a public adjuster to navigate and advocate on their behalf in order to get the needed results. Our family could not have rebuilt our home with the funds our insurance company provided, and we only have a home to return to because of ICRS’ efforts to hold our insurer accountable for the policy we had paid for. Throughout the claim, which lasted over a year, ICRS navigated the entire claim process with professionalism and care. Our family offers a sincere thank you to Scott, Misty, and the entire ICRS team.
FAQs
Frequently Asked Questions
What is a public adjuster and what do they do?
Here at ICRS, we help policyholders understand their rights. Discover the different types of insurance, the insurance claim process, and settlement tips from the National Association of Insurance Commissioners.
When should I hire a public adjuster?
How are public adjusters compensated?
How do public adjusters differ from insurance company adjusters?
Do I need a public adjuster if I already have an insurance agent or broker?
NEWS & ARTICLES
The Latest News
Read More
Read More
Read More